This page gives you the official NCERT Recording of Transactions-I Class 11 Accountancy chapter PDF — chapter 3 of Financial Accounting-I, where you first record real business transactions. The chapter runs about 53 printed pages starting at textbook page 45, and the official file is one tap below, hosted on ncert.nic.in.
The link above opens the official NCERT chapter file — the same edition NCERT publishes — so anything you study from this page matches the book in your bag.
| What the chapter holds | Count | Where it is used |
|---|---|---|
| Printed pages | 53 | |
| Sections in the chapter | 10 | |
| Figures with NCERT captions | 1 | |
| Tables | 103 | |
| Worked examples | 1 | solved step by step in our NCERT Solutions |
| Official NCERT PDF | Download the chapter PDF | the chapter exactly as NCERT publishes it |
Chapter at a Glance
Use the table below to see what the chapter file actually holds — its sections, figures, worked examples and exercise material.
Behind the numbers, the chapter follows one continuous path. It opens with learning objectives on page 45, moves through vouchers, the accounting equation, debit and credit rules, the journal, GST entries, the ledger and posting, and closes with the key terms, a summary, Test Your Understanding self-checks, exercises and answers on pages 87–88.
What This Chapter Covers: From Source Document to Ledger
This is the first chapter of the book where you actually record transactions instead of defining accounting terms. It follows one path: a business event produces evidence, that evidence is written first into the journal, and the journal entries are then transferred to individual accounts in the ledger.
The chapter’s sections, with the NCERT page where each begins:
- 3.1 Business Transactions and Source Document (p. 46) — what counts as a transaction and the documents that prove it happened.
- 3.1.1 Preparation of Accounting Vouchers (p. 47) — how that evidence is packaged into a voucher for the books.
- 3.2 Accounting Equation (p. 50) — the equality every transaction must preserve.
- 3.3 Using Debit and Credit (p. 53) — what debit and credit actually mean.
- 3.3.1 Rules of Debit and Credit (p. 54) — the five account types and their rules.
- 3.4 Books of Original Entry (p. 60) — why transactions are first recorded in the journal.
- 3.4.1 Journal (p. 61) — the format of a journal entry and how to write one.
- 3.5 The Ledger (p. 72) — where entries finally live.
- 3.5.1 Classification of Ledger Accounts (p. 75) — permanent versus temporary accounts.
- 3.6 Posting from Journal (p. 75) — the mechanics of transferring entries into the ledger.
The book also devotes a full block to Accounting Entries under Goods and Services Tax (pp. 70–73), placed between journalising and the ledger, because GST changes the way ordinary entries are written.
Key Concepts, Explained Step by Step
The seven ideas below are the chapter’s spine, in the order the book builds them. Read them in sequence once, then jump back to any one for revision.
Business Transactions and Source Documents
Before any entry can be written, a business must settle two questions: is this event actually a transaction, and what evidence proves it happened? This opening section answers both.
A business transaction is an exchange of economic consideration between parties, with a give aspect and a take aspect (NCERT, pp. 46–47). Paying cash is the give; receiving the goods is the take. Because every transaction has a two-fold effect, it is recorded in at least two accounts (p. 47).
Transactions are backed by source documents — the evidence on which all recording is based (p. 47):
- Cash memo — for retail purchases;
- Invoice or sales bill — for credit sales;
- Pay-in-slip — for money deposited into the bank;
- Cheque — for payments made through the bank;
- Salary slip — for salary payments.
For small out-of-pocket expenses where no outside document exists, the firm prepares its own voucher with the necessary details and gets it approved by an authorised person inside the firm (p. 47).
Original example: a chemist buys packing material for ₹2,000 cash. The seller’s cash memo is the source document; the give is ₹2,000 cash and the take is the packing material. The two-fold effect will later be a debit to an expense and a credit to cash.
Accounting Vouchers: Simple, Compound and Complex
A voucher is the internal document that carries a transaction into the books. The chapter shows three types so you can recognise which one a given transaction needs.
- Transaction voucher — one debit and one credit; this is a simple transaction (p. 47).
- Debit voucher — several debits against one credit (p. 48).
- Credit voucher — several credits against one debit (p. 48).
- Complex or journal voucher — several debits and several credits together (p. 49).
Vouchers have no set format — the design depends on the firm’s convenience, and different colours or fonts are used to tell them apart (p. 49). What every voucher must carry is this checklist (p. 50):
- a serial number in order;
- the date of the transaction, not the date of recording;
- the names of the accounts to be debited and credited;
- the amount in figures;
- an account-wise description of the transaction;
- the preparer’s name and signature;
- the authorising person’s name and signature.
The Accounting Equation: A = L + C
The accounting equation is the chapter’s central check. Whatever the business does, the equality below must never break — every transaction changes assets, liabilities or capital without destroying the balance.
What a business owns is called its assets (A); what it owes to outsiders is liabilities (L); what it owes to the proprietor is capital (C). The equation reads \(A = L + C\) (NCERT, p. 50).
Its two derivatives, \(A – L = C\) and \(A – C = L\), let you find a missing figure when one is unknown (p. 50). Because the equation mirrors the balance sheet, it is also called the balance sheet equation (p. 50).
Work through a fresh example to see the equation hold. Meera starts a boutique with these five transactions:
- Started business with cash ₹2,40,000 and stock worth ₹60,000.
- Deposited ₹1,50,000 of the cash into a bank account.
- Bought furniture for ₹45,000, paid by cheque.
- Bought goods worth ₹80,000 on credit from a supplier.
- Sold goods costing ₹20,000 for ₹32,000 on credit.
The effect of each transaction on the equation:
| Transaction | Effect on assets | Effect on liabilities | Effect on capital |
|---|---|---|---|
| 1. Cash and stock introduced | Cash +2,40,000; Stock +60,000 | No change | +3,00,000 |
| 2. Cash into bank | Cash −1,50,000; Bank +1,50,000 | No change | No change |
| 3. Furniture by cheque | Furniture +45,000; Bank −45,000 | No change | No change |
| 4. Goods on credit | Stock +80,000 | +80,000 (creditor) | No change |
| 5. Sale of goods on credit | Debtors +32,000; Stock −20,000 | No change | +12,000 (profit) |
Final position: Cash ₹90,000 + Bank ₹1,05,000 + Stock ₹1,20,000 + Furniture ₹45,000 + Debtors ₹32,000 = ₹3,92,000 of assets. Liabilities ₹80,000 plus capital ₹3,12,000 = ₹3,92,000. Both sides stay equal at every step — that is what the accounting equation guarantees (p. 52).
Rules of Debit and Credit
The most common confusion in this chapter is thinking debit means increase and credit means decrease. It does not. Debit is the left side of an account and credit is the right side (NCERT, p. 53); their effect depends on the type of account you are looking at.
In its simplest form an account looks like the letter T, with the left side for debit (Dr.) and the right side for credit (Cr.) (pp. 53–54). All accounts fall into five categories: assets, liabilities, capital, expenses/losses, and revenues/gains (p. 54).
| Type of account | Debit (left side) | Credit (right side) |
|---|---|---|
| Assets | Increases the account | Decreases the account |
| Liabilities | Decreases the account | Increases the account |
| Capital | Decreases the account | Increases the account |
| Expenses / Losses | Increases the account | Decreases the account |
| Revenues / Gains | Decreases the account | Increases the account |
(NCERT, p. 55) So the same account can be debited in one entry and credited in the next. Take a cash account: when the business receives ₹2,000, cash increases and is debited; when it pays ₹800, cash decreases and is credited. Cash is debited for an increase because cash is an asset. A liability behaves in reverse — it is credited for an increase.
NCERT itself asks the question “Does debit always mean increase and credit always mean decrease?” and the answer is no (pp. 57, 98).
The double entry check follows automatically: in every entry, total debits must equal total credits (p. 53). If they do not match, the entry is wrong.
Books of Original Entry and the Journal
Real businesses do not write straight into accounts. Each transaction is first recorded in the journal — the book of original entry — in the order it happens, and is only later transferred to the ledger. Recording in the journal is called journalising (p. 61).
Because most transactions repeat, the journal is subdivided into the journal proper, the cash book, and the day books — purchases, sales, purchase returns, sales returns, bills receivable and bills payable. The book says the cash book and day books are dealt with in detail in chapter 4 (p. 61), which you can study here: Recording of Transactions-II notes.
The journal has five columns: Date, Particulars, L.F., Debit Amount and Credit Amount (Fig 3.5, p. 62). Writing an entry follows a fixed drill (pp. 62–63):
- The account to be debited is written first, with ‘Dr.’ at the end of the particulars.
- The account to be credited comes on the next line, indented and prefixed ‘To’.
- A brief narration — the description of the transaction — is written below.
- A line is drawn across the particulars column to close the entry.
The L.F. column records the ledger page where the account appears, and is filled only at the time of posting, not while journalising (p. 62).
A simple journal entry involves exactly two accounts. A compound journal entry involves more than one account on at least one side (p. 63). Original example: a repair shop buys tools for ₹9,500, paying ₹3,000 cash and owing the rest. One account is debited, two are credited:
| Particulars | Debit ₹ | Credit ₹ |
|---|---|---|
| Tools A/c Dr. | 9,500 | |
| To Cash A/c | 3,000 | |
| To Creditors A/c | 6,500 |
One key point NCERT stresses: when goods are bought on credit, the account debited is Purchases, not Goods. The goods account is divided into five accounts — purchases, sales, purchases returns, sales returns and stock (p. 63) — so each kind of movement has its own place.
Goods and Services Tax in Journal Entries
GST is a tax on supplies, and the journal must record it separately from the price of the goods. The rule to remember: what you pay on purchases is an input, what you charge on sales is an output.
- Intra-state transactions (within the same state) split the tax equally into CGST and SGST (pp. 70–71).
- Inter-state transactions (between states) use a single IGST (p. 72).
- On purchases and expenses, the input tax accounts are debited: Input CGST, Input SGST or Input IGST.
- On sales, the output tax accounts are credited: Output CGST, Output SGST or Output IGST.
Original example: goods worth ₹40,000 are bought within the state, with CGST and SGST at 6% each. CGST = 6% of ₹40,000 = ₹2,400, and SGST is the same ₹2,400. The journal entry is:
| Particulars | Debit ₹ | Credit ₹ |
|---|---|---|
| Purchases A/c Dr. | 40,000 | |
| Input CGST A/c Dr. | 2,400 | |
| Input SGST A/c Dr. | 2,400 | |
| To Creditors A/c | 44,800 |
At the end of the period the amount actually payable is the output GST minus the input GST that can be set off (pp. 70–71). The set-off order is fixed (p. 73):
IGST credit is applied first against IGST, then against CGST, and the balance, if any, against SGST.
In the book’s own illustration the firm did not pay the full output CGST on its sales; it paid only the difference after its input CGST had been set off (p. 71). The same pattern applies on the SGST side.
The Ledger and Posting from Journal
The journal tells you what happened and when. The ledger tells you what a single account looks like — what a customer owes, or what the firm owes a supplier. A ledger is the principal book: the collection of all the accounts, each opened on its own page (p. 72).
This is the ledger’s utility: the amount due from a customer or payable to a supplier can be found only in the ledger, because the journal records in chronological order and defies classification (p. 73).
The journal and the ledger differ on five points (p. 75):
| Basis | Journal | Ledger |
|---|---|---|
| Place in sequence | Book of first (original) entry | Book of second entry |
| Nature of record | Chronological | Analytical |
| Legal evidence | Greater importance, as book of source entry | Lesser |
| Basis of classification | Transaction | Account |
| Process of recording | Journalising | Posting |
Ledger accounts are also classified. Permanent accounts — assets, liabilities and capital — are balanced and carried forward to the next period, and appear in the balance sheet. Temporary accounts — revenues and expenses — are closed at the end of the period by transfer to the trading and profit and loss account (p. 75).
Posting is the transfer of entries from the journal to the ledger (p. 76), done in five steps:
- Locate in the ledger the account to be debited.
- Enter the date of the transaction in the date column.
- Enter in the particulars column the name of the account through which it came — the contra account.
- Enter the journal page number in the J.F. column; on the journal side, write the ledger page number.
- Enter the amount in the amount column.
(NCERT, p. 76) Trace one original entry: Ravi sells goods worth ₹7,500 on credit to Aman. The journal entry debits Aman’s A/c ₹7,500 and credits Sales A/c ₹7,500.
In the ledger, Aman’s account receives the debit-side posting — particulars ‘Sales’, amount ₹7,500 — and that balance is what Aman owes. The Sales account receives the credit-side posting — particulars ‘Aman’, amount ₹7,500 — and that is the revenue earned.
The credit side is posted the same way as the debit side: locate the account, enter the date, write the contra account in the particulars, fill the folio columns, enter the amount. Both sides of the journal entry have now found their ledger home.
Figure Walkthrough: The T-Account (NCERT Fig. 3.4)
The T-account is the one diagram the chapter renders as an image, and it is the shape behind every account you will open. NCERT prints it as Fig 3.4 on page 54.
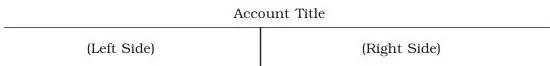
Read the figure as two columns: the left side is debit, abbreviated Dr., and the right side is credit, abbreviated Cr. (p. 53). Every account you open in the ledger — Cash, Capital, Bank, Furniture, Plant and Machinery — takes this shape (pp. 76–78).
The T shape matters because each side collects entries of one kind, and the balance of an account is the difference between the two sides. NCERT’s own example: for a customer’s account, all goods sold appear on the left (debit) side and all payments received on the right; the difference is the balance — the amount due from that customer (pp. 53–54).
That is how a T-account turns a long list of entries into one readable figure.
The chapter also prints specimen voucher formats as Figs 3.1–3.3, the journal format as Fig 3.5 and the ledger format as Fig 3.6 — these are printed tables, described in the sections above, and only the T-account is rendered as a diagram here.
Key Accounting Terms Defined in This Chapter
These are the chapter’s own Key Terms (p. 87), with the page where each first appears. Use them as quick lookups while you do the exercises.
| Term | What it means | Page |
|---|---|---|
| Source document | The evidence of a transaction — cash memo, invoice, sales bill, pay-in-slip, cheque, salary slip | p. 47 |
| Debit | The left side of an account, abbreviated Dr. | p. 53 |
| Credit | The right side of an account, abbreviated Cr. | p. 53 |
| Account | A record of increases and decreases in one item, in its simplest form a T-account | p. 54 |
| Accounting equation | A = L + C — assets always equal liabilities plus capital | p. 50 |
| Books of original entry | The books where transactions are first recorded, in chronological order | p. 61 |
| Journal | The basic book of original entry | p. 61 |
| Journalising | The process of recording a transaction in the journal | p. 61 |
| Narration | The brief description of the transaction written below the account names in an entry | p. 63 |
| Ledger | The principal book — the collection of all accounts, each on its own page | p. 73 |
| Posting | The process of transferring entries from the books of original entry to the ledger | p. 76 |
Common Mistakes Students Make in Recording Transactions
Each error below is one NCERT itself corrects through its Test Your Understanding blocks, whose answers sit at the end of the chapter (p. 98).
| Mistake | Correct rule | How to check your work |
|---|---|---|
| “Debit always means increase.” | Debit is just the left side. It increases assets and expenses, but it decreases liabilities, capital and revenues (pp. 53–55). | Name the account type first, then decide the side. Cash is debited when it comes in, credited when it goes out. |
| Debiting “Goods” when goods are bought. | Debit Purchases A/c, not Goods A/c. Goods are split into purchases, sales, purchases returns, sales returns and stock (p. 63). | Ask: did goods come in (Purchases debit) or go out (Sales credit)? |
| Filling the L.F./J.F. column while journalising. | The folio columns are filled only at posting time, when the ledger page is known (pp. 62, 76). | The journal’s L.F. column should still be blank when you finish the entry. |
| Omitting the narration or the closing line. | Every journal entry carries a brief narration and a line drawn below it (p. 63). | Read the entry aloud — would someone else know what happened? |
| Setting off GST in the wrong order. | Output GST is set off against input GST; IGST credit goes first against IGST, then CGST, then SGST (p. 73). | Set the credit you hold (input) against the liability you owe (output) in the printed order. |
| Forgetting the discount account in full settlement. | When ₹12,000 due is settled by ₹11,500, the ₹500 difference is discount allowed, which is debited (Illustration 5, p. 83). | Add the amount received and the discount: the sum must equal the original amount due. |
Exam Notes: What to Practise from This Chapter
Below is what each block of the closing exercises actually drills, so you can practise in a useful order. No question is guaranteed on any paper — this is a map of the chapter’s own exercise material.
- Short Answers (p. 88) — concepts and definitions in one or two sentences.
- Long Answers (pp. 88–89) — an explanation supported by a specimen or an example.
- Analysis of Transactions (Q. 1–10) (pp. 88–92) — accounting equation practice: prepare the equation and track each effect.
- Journalising (Q. 11–15) (pp. 92–94) — simple, compound and adjustment entries, including discount and returns.
- Posting (Q. 16–22) (pp. 94–98) — journal entries followed by ledger posting, including discount, returns and GST entries.
A practical revision order: master the five account types and the debit/credit table first, then the accounting equation, then journalising, then posting, then GST. The Test Your Understanding answers at the end of the chapter (p. 98) make a fast self-check.
One note on scope: textbook contents and the examinable syllabus are not always identical — check the current official syllabus before deciding what to prepare in detail.
What the Chapter Concludes
The chapter closes with a summary keyed to its learning objectives (pp. 87–88). What it comes down to is six points:
- Source documents — invoices, bills, cash memos and vouchers — are the basis and evidence of every transaction recorded (p. 87).
- The accounting equation \(A = L + C\) is the equality that must never break; every transaction keeps assets equal to liabilities plus capital (p. 87).
- Debit and credit are the left and right sides of an account; whether they increase or decrease depends on the account’s nature (p. 87).
- The journal is the book of original entry; recording in it is journalising (p. 87).
- The ledger is the principal book; transferring entries into it is posting (p. 88).
- GST is recorded separately as input and output CGST, SGST and IGST, with IGST credit set off first against IGST, then CGST, then SGST (p. 73).
Related Resources
This listing is maintained for the 2026-27 academic session using the NCERT textbook information available to us. NCERT remains the authority for confirming the latest edition.
Continue with the right next page, depending on what you need:
- Chapter-by-chapter support for this book: Class 11 Accountancy notes.
- All subjects for the class: Class 11 hub.
- The ideas behind this chapter come from chapter 2: Theory Base of Accounting notes.
- The book itself says the cash book and other day books are dealt with in detail in chapter 4 (p. 61): Recording of Transactions-II notes.
- Every class and subject on the site: main notes index.
The official chapter page on ncert.nic.in hosts the PDF of Recording of Transactions-I and is the authoritative source for the edition, so opening it there lets you verify that your copy matches the file.
Reference: NCERT Class 11 Accountancy textbook, chapter 3, official edition on ncert.nic.in.
Sources and Data Verification
- This page describes the NCERT Class 11 Accountancy textbook Financial Accounting-I, Chapter 3, official NCERT edition.
- It covers this chapter only — not Chapters 1 and 2, and not the second book, Financial Accounting-II.
- It is maintained for the current academic session using NCERT’s published material.
- NCERT settles textbooks, editions and PDFs; CBSE settles the curriculum, syllabus and examinations. Page numbers follow the printed NCERT edition.
Frequently Asked Questions
Why is the purchases account debited instead of the goods account when goods are bought on credit?
Because the goods account is divided into five accounts — purchases, sales, purchases returns, sales returns and stock — so each kind of movement has its own place (p. 63). When goods come in, the purchases account is debited; when they go out, the sales account is credited; returns have their own accounts.
If everything went into one “goods” account, you could not tell what was bought, sold, returned or still in stock.
Does debit always mean increase and credit always mean decrease?
No. Debit is the left side of an account and credit is the right side; whether a debit increases or decreases the balance depends on the account type (pp. 53–54). Cash is debited for an increase but credited for a decrease; a liability is credited for an increase. NCERT’s own Test Your Understanding answers this exact question with “No” (p. 98).
What is the difference between the journal and the ledger?
The journal is the book of original entry where transactions are recorded in chronological order; the ledger is the principal book where every account is collected in one place (pp. 61, 72). Recording in the journal is journalising, and transferring to the ledger is posting (p. 75). The five-point comparison table in this page’s Key Concepts section sets them out side by side.
How are CGST, SGST and IGST recorded in journal entries?
Intra-state transactions split the tax into CGST and SGST; inter-state transactions use IGST (pp. 70–72). On purchases, the input tax accounts are debited (Input CGST, Input SGST, Input IGST); on sales, the output tax accounts are credited (Output CGST, Output SGST, Output IGST). At the end, output GST is set off against input GST and only the balance is paid (pp. 70–71).
When is a compound journal entry used?
When more than one account is debited or credited in a single transaction (p. 63). It is used whenever one side of the transaction touches several accounts — for example, an asset bought partly for cash and partly on credit, so the asset account is debited and both cash and the creditor are credited.
What is the accounting equation and why must it always balance?
The accounting equation is \(A = L + C\): the assets of a business always equal its liabilities plus its capital (p. 50). Every transaction has a two-fold effect that changes at least two elements of the equation, so the equality never breaks. This is why NCERT also calls it the balance sheet equation (p. 50).
Explore Class 11 Accountancy Books
- Previous: Theory Base of Accounting
- Next: Recording of Transactions-II
Related chapters: