This page carries NCERT Class 12 Business Studies Part I, Chapter 8, Controlling — the official PDF and a section-by-section explanation of what the chapter teaches. The chapter runs from NCERT page 200 to page 213, opening with an airline departure-control caselet and building up to the five-step controlling process. The PDF link is right below; the teaching starts after it.
Download the Controlling Class 12 Chapter PDF
| What the chapter holds | Count | Where it is used |
|---|---|---|
| Printed pages | 14 | |
| Figures with NCERT captions | 1 | |
| Tables | 2 | |
| Official NCERT PDF | Download the chapter PDF | the chapter exactly as NCERT publishes it |
This is the official chapter file, offered first because it is what you searched for. Open the NCERT Class 12 Business Studies Chapter 8 Controlling PDF to read the chapter exactly as printed, from the opening departure control systems caselet to the closing exercise questions — it is the same text every page reference on this page points to.
Controlling Class 12 Chapter at a Glance
The table below shows how much this chapter holds — its sections, figures, tables and exercise sets — so you can see the chapter’s shape before opening the full text. It is the single place those counts appear, so nothing on the rest of this page repeats them.
What This Chapter Contains: From an Airline Caselet to Corrective Action
The chapter moves in a clear order: it starts with a real-world case, defines controlling, argues why it matters and where it fails, then teaches the process step by step. Use the page numbers below to jump straight to the part you need.
- Departure Control Systems caselet (p. 201) — the airline software that updates a passenger’s reservation through check-in, boarding and baggage handling; the chapter’s proof that controlling runs inside everyday operations.
- Learning objectives (p. 201) — the five things the chapter expects you to be able to do by the end.
- Meaning of controlling (p. 202) — the definition, with the two qualities attached to it: goal oriented and pervasive.
- Importance of controlling (pp. 202-204) — six reasons a good control system helps an organisation, with the computer-monitoring box on pp. 203-204.
- Limitations of controlling (pp. 204-205) — four honest limits, with the figure on p. 204 sitting in the middle of them.
- Relationship between planning and controlling (pp. 205-206) — why the two are called inseparable twins.
- Controlling process (pp. 206-210) — the five steps, ending with corrective action and a remedial plan-of-action box on p. 210.
- Standards in functional areas (p. 208) — a four-column table of the standards used to gauge production, marketing, HR and finance performance.
- Key terms (p. 210) and Summary (p. 211) — the definition list and the chapter’s own recap.
- Exercise set (pp. 212-213) — very short, short and long answer questions covering everything above.
Key Concepts: Controlling Class 12 Term by Term
The chapter is short on formulas and long on definitions and sequence. These are the ideas it is built on, explained the way a teacher walks a stuck student through them. Follow along in your own book using the page numbers given.
Meaning of Controlling: A Goal Oriented and Pervasive Function
Why the airline caselet matters: the chapter opens with Departure Control Systems (DCS), the software that runs airport check-in. A DCS records a passenger’s reservation (the PNR), then updates it as the passenger checks in, boards and flies.
Anyone who does not match the record is flagged — that is controlling in everyday form: checking what actually happened against what was planned.
Controlling means ensuring that activities in an organisation are performed as per the plans, and that resources are used effectively and efficiently to reach predetermined goals. That is why the book calls it a goal-oriented function — it exists to get the organisation to a target, not to punish mistakes (NCERT, p. 202).
- It is pervasive. Every manager at every level — top, middle and lower — must control activities in their own area. It applies in schools, hospitals, the military, clubs and business alike (NCERT, p. 202).
- It is not the last function. Controlling finishes one management cycle and brings the cycle back to planning: the deviations it detects and the corrective actions it takes become the basis of better future plans (NCERT, p. 202).
Importance of Controlling: Six Ways a Good Control System Helps
A good control system exists for six concrete reasons. Know all six by name — a long-answer question on importance expects each one explained.
- Accomplishing organisational goals — controlling measures progress, surfaces deviations and guides corrective action, keeping the organisation on the right track (NCERT, p. 202).
- Judging accuracy of standards — it checks whether the standards set were realistic and revises them when the environment changes (NCERT, p. 203).
- Making efficient use of resources — work done to predetermined norms reduces wastage and spoilage (NCERT, p. 203).
- Improving employee motivation — employees who know in advance what is expected and how they will be appraised perform better (NCERT, p. 203).
- Ensuring order and discipline — a close check on activities discourages dishonest behaviour. This is the point behind the chapter’s computer-monitoring box, in which a New York import-export firm caught two employees who had embezzled about $3 million over two and a half years (NCERT, pp. 203-204).
- Facilitating coordination in action — pre-determined standards in each department pull every effort in one direction, so overall objectives are met (NCERT, p. 204).
Koontz and O’Donnell defined managerial control as “the measurement of accomplishment against the standard and the correction of deviations to assure attainment of objectives according to plans” (NCERT, p. 203). If an answer needs the meaning, that definition and the book’s own simpler line both work.
Limitations of Controlling: Four Reasons Control Systems Fail
This section answers the question “what problems does an organisation face in implementing an effective control system?” The chapter lists four limitations of controlling (NCERT, pp. 204-205).
- Difficulty in setting quantitative standards. Morale, job satisfaction and human behaviour resist measurement, so performance cannot always be compared cleanly against a number.
- Little control over external factors. Government policies, technological change and competition are outside an enterprise’s control.
- Resistance from employees. Employees often see control as a restriction on freedom — for instance, they may object to being watched on CCTV.
- Costly affair. Control takes money, time and effort. A small enterprise may not be able to justify the expense, so managers must ensure costs never exceed the benefits the system brings.
The figure on NCERT page 204, walked through below, sits inside this discussion. The chapter also includes a box on the control system at FedEx as a success story — the same tools working well in a large operation.
Planning and Controlling: The Inseparable Twins of Management
Planning without controlling is meaningless, and controlling without planning is blind — that is the book’s own one-line summary of the relationship (NCERT, p. 205). Here is the comparison in table form, the one worth copying into your notes.
| Point of comparison | Planning | Controlling |
|---|---|---|
| What it does | Sets objectives and decides the course of action | Checks whether actions match the plan |
| Nature | Prescriptive — prescribes what should happen | Evaluative — judges what did happen |
| Direction of view | Forward-looking, prepared for the future | Backward-looking, examines past performance |
| What it gives the other | Provides the standards control works with | Provides feedback that improves future plans |
| Place in the management cycle | Initiates the cycle | Completes one cycle and returns to planning |
Then comes the nuance the exam wants: the simple “planning looks ahead, controlling looks back” line is only partially correct. Planning is guided by past experience, and the corrective action control initiates aims at future performance — so both functions are backward-looking and forward-looking at once (NCERT, p. 205).
Finally, the two reinforcing relationships printed on page 206: planning based on facts makes controlling easier and more effective; and controlling improves future planning by feeding back what past experience revealed.
The Controlling Process: Five Steps from Standards to Corrective Action
This is the heart of the chapter, and the long-answer exercise on “the process of control” tests it directly. The five steps run from NCERT pages 206 to 210.
- Setting performance standards. Standards are the criteria against which actual performance is measured — the benchmarks the organisation works towards (p. 206). They can be quantitative (cost, revenue, units, time) or qualitative (goodwill, motivation), and they should stay flexible enough to modify when the environment changes (p. 207).
- Measurement of actual performance. Measure objectively, in the same units as the standards, so comparison is easy. Wherever possible measure during performance, not after the task ends — and in large organisations use sample checking instead of inspecting every piece (p. 207).
- Comparison of actual performance with standards. This reveals the deviation between actual and desired results. Comparison is far easier when standards are quantitative (pp. 207-208).
- Analysing deviations. A manager decides the acceptable range of deviation first. Small deviations within the range are normal; deviations in key areas demand urgent attention. This is where critical point control and management by exception operate (p. 208).
- Taking corrective action. If the deviation stays within acceptable limits, no action is needed. Beyond the limits — especially in important areas — the manager must act: retraining, extra workers, overtime, or revising the standards themselves if the deviation cannot be fixed by action (pp. 209-210).
Worked example — the five steps in a garment factory. Follow one cycle of the process from standard to corrective action.
- Step 1 — standard: 1,200 shirts per shift, with an acceptable deviation of 3 per cent.
- Step 2 — measurement: actual output for the shift is 1,080 shirts.
- Step 3 — comparison: the shortfall is 120 shirts, which is 10 per cent below standard — far beyond the 3 per cent limit.
- Step 4 — analysis: production logs point to heavy absenteeism and a delayed fabric delivery as the causes.
- Step 5 — corrective action: overtime for the next two shifts and retraining for the new cutting-line operators; the standard itself stays unchanged because the causes were operational, not unrealistic.
Step 4 Inside Out: Critical Point Control and Management by Exception
Both tools live inside Step 4 of the process and answer the same question: which deviations deserve a manager’s attention? Students mix them up constantly — one is about which areas to watch, the other about which deviations to act on.
Critical point control starts from the fact that checking every activity is neither economical nor easy. Control should focus on key result areas (KRAs) that are critical to the organisation’s success — if something goes wrong at a critical point, the whole organisation suffers (NCERT, p. 208).
Management by exception starts from the belief that an effort to control everything results in controlling nothing. Only significant deviations that cross the permissible limit are brought to management’s notice (NCERT, p. 208).
| Point | Critical point control | Management by exception |
|---|---|---|
| Question it answers | Which areas should we watch? | Which deviations should we act on? |
| Focus | Key result areas critical to success | Deviations beyond the permissible limit |
| Basis | Not every activity can be checked economically | Not every deviation is significant |
| Direction of attention | Selects the areas to monitor | Escalates only serious deviations |
Worked example — management by exception. A company fixes the acceptable deviation in labour cost at 1.5 per cent. Actual labour cost rises 3.8 per cent — beyond the limit, so it is reported to top management for priority action.
Meanwhile stationery expenses rise 11 per cent, but the absolute amount is tiny, so the same rise is settled at the departmental level and never escalates. The principle separates the significant from the routine.
Because the two tools work together, the chapter lists four advantages of using them (NCERT, p. 209): they save managerial time because only significant deviations are dealt with; they focus attention on important areas, making better use of managerial talent; they leave routine problems to subordinates, which facilitates delegation and raises morale; and they identify critical problems needing timely action to keep the organisation on track.
Standards Used in Functional Areas to Gauge Performance
Before Step 2 can measure anything, Step 1 needs a benchmark. Standards are those benchmarks — the criteria against which actual performance is judged (NCERT, p. 206).
Quantitative standards are easy to check: cost, revenue, units produced and sold, time per task. Qualitative standards like goodwill and motivation are harder, so the book says to define them in measurable terms wherever possible (NCERT, p. 207).
The chapter’s own example turns customer satisfaction in a self-service fast-food chain into waiting time at each stage. A parallel would be a hotel measuring guest satisfaction as the average minutes between arrival and room handover.
NCERT’s page 208 table gives the standards used across four functional areas:
| Production | Marketing | Human Resource Management | Finance and Accounting |
|---|---|---|---|
| Quantity | Sales volume | Labour relations | Capital expenditures |
| Quality | Sales expense | Labour turnover | Inventories |
| Cost | Advertising expenditures | Labour absenteeism | Flow of capital |
| Individual job performance | Individual sales-person’s performance | — | Liquidity |
That table directly answers the very short-answer exercise asking for any two standards a company can use to evaluate its finance and accounting department: capital expenditures, inventories, flow of capital and liquidity all work.
Figure Walkthrough: “Remain Level Headed Even When Things Go Wrong”
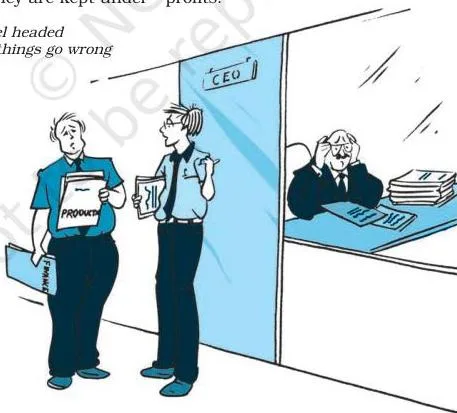
This is the one graphic the chapter carries, and its position is meaningful: it appears on page 204, in the middle of the limitations discussion. The book is telling you that even when control systems fail or employees resist them, the manager’s job is to stay calm and analytical.
That temperament runs through both halves of the process. Step 4 (analysing deviations) demands a level head because deviations are normal — the job is to trace causes, not to panic. And the computer-monitoring case worked because managers collected evidence dispassionately before acting, exactly the attitude the figure asks for.
Definitions: Key Terms from NCERT Pages 210 to 211
The chapter closes with a key-terms box and a summary. These are the terms, in the order the chapter uses them, ready to write in an exam answer.
- Controlling — ensuring that actual activities conform to planned activities (NCERT, p. 211).
- Standards — the criteria, or benchmarks, against which actual performance is measured (NCERT, p. 206).
- Deviation — the difference between standard performance and actual performance that comparison reveals (NCERT, p. 208). This word is the answer to the very short-answer question asking which term indicates that gap.
- Critical point control — focusing control on key result areas that are critical to the organisation’s success (NCERT, p. 208).
- Management by exception — bringing only significant deviations beyond the permissible limit to management’s notice (NCERT, pp. 208-209).
The techniques of managerial control — the subject of a long-answer exercise — fall into two groups, exactly as the summary groups them (NCERT, p. 211):
- Traditional techniques: personal observation, statistical reports, breakeven analysis, budgetary control.
- Modern techniques: return on investment, ratio analysis, responsibility accounting, management audit, PERT and CPM, management information system.
This page does not expand each technique because the chapter itself does the job in detail — open the PDF at the Key Terms box (p. 210) and the Summary (p. 211) when you need those full explanations for a long answer.
Common Mistakes Students Make in This Chapter
These five errors come straight from points the book takes care to correct. Fix them before they cost marks.
| Mistake | Correct rule | How to check your answer |
|---|---|---|
| “Controlling is the last function of management” | Controlling completes one cycle of the management process and brings it back to planning, improving the next cycle’s plans (NCERT, p. 202). | Ask: what happens after corrective action? The answer is better future planning. |
| “Planning looks ahead; controlling looks back” | Both are backward-looking and forward-looking — planning is guided by past experience, and corrective action aims at future performance (NCERT, p. 205). | Can you name planning’s input from the past and control’s target in the future? |
| “Every deviation needs corrective action” | Only deviations beyond the acceptable range, especially in key areas, demand action; small deviations are expected (NCERT, p. 208). | Compare the deviation’s size against the permissible limit before recommending action. |
| Mixing up critical point control and management by exception | One selects the areas to watch (key result areas); the other decides which deviations to escalate (NCERT, pp. 208-209). | Ask two questions: “which area?” → critical point control; “how big is the deviation?” → management by exception. |
| “Measure performance only after the task is done” | Measure during performance wherever possible — for example, checking each part before assembly (NCERT, p. 207). | Can the check happen while the work is in progress? If yes, it should. |
Exam Notes: How to Prepare This Chapter for Your Tests
No page can promise what will appear in your exam, but the chapter’s own exercise set shows what NCERT expects you to be able to do. Here is how the questions map to the concepts (NCERT, pp. 212-213).
Very short answers test recall: the meaning of controlling (Q1); the principle for dealing with deviations — management by exception (Q2); a situation in which control loses effectiveness, such as where standards resist quantitative measurement (Q3); two finance and accounting standards from the page 208 table (Q4); and the term for the gap between standard and actual — deviation (Q5).
Short answers test explanation: the “planning is looking ahead, controlling is looking back” comment (Q1) needs the both-look-both-ways argument from pages 205-206; “an effort to control everything may end up in controlling nothing” (Q2) is management by exception; management audit (Q3) is a modern technique from the page 210 key-terms box; and the Mr Arfaaz case (Q4) is a direct application of management by exception — the book’s own hint says so.
Long answers test the process and the big relationships: the steps of control (Q1) from pages 206-210; the techniques (Q2); importance plus the problems in implementing control (Q3); the planning-controlling relationship (Q4); and two scenario applications — M Ltd’s mobile phones (Q5) and Mr Shantanu’s garments (Q6), which ask for the features and importance of controlling applied to a situation.
For a full-marks written answer on the process, practise narrating all five steps with a fresh example rather than a memorised one — the worked example above is a model. And note that textbook contents and the examinable syllabus are not always identical — check the current official CBSE Business Studies syllabus for what is examinable this session.
Quick Recall: The Controlling Chapter in One Page
A night-before recap, built from the chapter’s own summary on page 211. Keep this list open while you revise.
- Controlling ensures actual activities conform to planned activities.
- Why it matters (six): accomplishes organisational goals, judges accuracy of standards, makes efficient use of resources, improves employee motivation, ensures order and discipline, facilitates coordination in action.
- Its limits (four): difficulty setting quantitative standards, little control over external factors, employee resistance, costly affair.
- The five-step process: setting performance standards, measuring actual performance, comparing actual with standards, analysing deviations, taking corrective action.
- Remember the order with: “Smart Managers Compare And Correct” — Set standards, Measure, Compare, Analyse, Correct.
- Planning and controlling are inseparable twins: plans are the basis of control, and control keeps even the best plans from going astray.
- Techniques, traditional: personal observation, statistical reports, breakeven analysis, budgetary control.
- Techniques, modern: return on investment, ratio analysis, responsibility accounting, management audit, PERT and CPM, management information system.
Related Resources: Other Class 12 Business Studies Chapters
This listing is maintained for the 2026-27 academic session using the NCERT textbook information available to us. NCERT remains the authority for confirming the latest edition.
Controlling is the function that checks up on everything else, so it connects most naturally to the chapters that set work in motion.
- Directing (Chapter 7 of the same book) covers the motivation, leadership and communication that get employees moving; controlling is what measures whether that direction achieved results.
- Business Studies Class 12 notes hub — the full set of chapters in this textbook, with Planning (Chapter 4) as the natural pair to this one.
- Class 12 hub — notes across all your Class 12 subjects.
- CBSE notes home — every class and subject in one place.
For the official textbook, NCERT’s portal at ncert.nic.in/textbook.php holds the complete Business Studies Part I book, and the chapter-specific file is the PDF linked at the top of this page.
Sources and Data Verification
- The figures on this page describe the NCERT Class 12 Business Studies Part I textbook, Chapter 8 Controlling, NCERT pages 200-213.
- This page covers that one chapter only — not the other books in the Business Studies series.
- The listing is maintained for the current academic session using the NCERT information available to us.
- NCERT settles textbook editions, contents and official PDFs; CBSE settles curriculum, syllabus and examinations.
Frequently Asked Questions: Controlling Class 12
What is the meaning of controlling in class 12 business studies?
Controlling means ensuring that activities in an organisation are performed as per the plans, and that resources are used effectively and efficiently to reach predetermined goals. The book adds two labels to this definition: controlling is goal oriented, and it is pervasive — every manager at every level performs it (NCERT, p. 202).
Why is controlling called a pervasive function of management?
Because it is performed by every manager at every level — top, middle and lower — over the activities in their own area. It is also pervasive across organisations: it operates in educational institutions, hospitals, the military, clubs and business firms alike (NCERT, p. 202).
What are the five steps of the controlling process?
The five steps are setting performance standards, measuring actual performance, comparing actual performance with standards, analysing deviations, and taking corrective action (NCERT, pp. 206-210). A useful order-mnemonic is “Smart Managers Compare And Correct” — Set, Measure, Compare, Analyse, Correct.
What is the difference between critical point control and management by exception?
Critical point control decides which areas to watch — the key result areas critical to success — because checking every activity is neither economical nor easy. Management by exception decides which deviations to act on: only those beyond the permissible limit are brought to management’s notice (NCERT, pp. 208-209).
Is controlling the last function of management?
No. Controlling completes one cycle of the management process and brings the cycle back to planning. The deviations it finds and the corrective action it takes become the basis of better planning in the next period (NCERT, p. 202).
Reference: NCERT Class 12 Business Studies textbook, chapter 8, official edition on ncert.nic.in.
Explore Class 12 Business Studies Books
Related chapters:
- Nature and Significance of Management
- Principles of Management
- Business Environment